GTRegs is a regulatory monitoring tool for the Swiss financial market. It supports board members, executives, risk and compliance officers at regulated financial institutions in systematically classifying regulatory developments.
Filter insights by:
Popular Topics
Featured Content
This article provides an overview of the implementation of the EU Anti-Money Laundering (AML) Package in Liechtenstein, including the repeal of the current SPG and the introduction of the new Anti-Money Laundering Act (AMLA). It outlines the key regulatory changes affecting financial and non-financial entities, highlights the expanded scope of obliged entities, and explains stricter due diligence, reporting, and compliance requirements. The article also addresses the role of supervisory authorities, updated risk classification rules, and the expected timeline for implementation, helping market participants assess their readiness and adapt their internal AML frameworks accordingly.
On 1 January 2026, Egon Hutter will take over the role of CEO from Erich Bucher, who is leaving the company for retirement.
Our latest insights
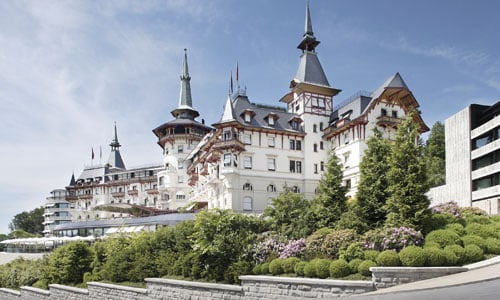
This March, Grant Thornton Switzerland/Liechtenstein presented itself for the first time as co-partner of the “FinTech 2019 – Beyond Banking” finance and business forum. This year’s FinTech conference was held on Thursday, 14 March 2019 at The Dolder Grand in Zurich which some 280 people attended. The conference was dedicated to the ongoing digital evolution of the financial sector and addressed initial findings. Renowned experts presented specific business cases from the world of Fintech and Blockchain as well as from digital-native industries.
The number of young companies founded (start-ups) continues unabated. Switzerland is a world leader in innovation thanks to its renowned universities. From the idea to the launch of a marketable product or service, however, it is a rocky road to overcoming hurdles in many different areas. What is more, mistakes made in the start-up phase can lead to problems later. Grant Thornton's experienced lawyers know what it takes to implement a business idea and can provide comprehensive advice to start-up companies with the support of other internal specialists (e.g. tax or transaction services).
From pricing and reputational risks to the threat of systems overload and cash flow disruption, indirect taxation is nothing like as easy as it seems. Almost everything that makes valueadded tax (VAT) and goods and services tax (GST) attractive to governments can make it a headache for businesses.
You are sure to have already considered one or two questions about retirement planning - or put off the topic until later. Often, actual planning is only started shortly before reaching retirement age. This is understandable because the closer retirement approaches, the more precisely one’s financial future can be structured. Nevertheless, early clarification is worthwhile, as younger people have much more scope for adjustments than they do shortly before retirement.
On 16 January 2015, the Swiss Federal Department of Finance published the revised wording of the federal expatriate ordinance which became effective on federal level on 1 January 2016. Generally, the competent cantonal tax authorities have adapted their assessment guidelines on municipal and cantonal level accordingly. The definition of an expatriate will be narrower and the tax deductible deductions expatriates can claim will be restricted.
By end of 2014, Swiss voters decided by a clear majority to maintain the lump-sum taxation regime. At federal level the requirements to qualify for being taxed under the lump-sum regime will be slightly amended. Cantonal regulations also consider adjustments to ensure an attractive and pragmatic lump-sum taxation regime for selected individual tax payers.
After the Energy Act was passed by Parliament and approved by more than 58% of the Swiss electorate in a referendum, the Swiss Federal Council amended the Property Costs Regulation for direct federal tax among others. In particular, this regulation defines the tax deductions newly adopted in the Energy Act such as the restoration expenses incurred in connection with a replacement construction. The provisions enter into force on 1 January 2020.
We are seeing many changes relating to registration requirements, digital reporting requirements, the approach to audits and compliance by tax authorities and the approaches to taxing the digital economy. It has been said that we are now living in a volatile, uncertain, complex and ambiguous (VUCA) world, and in relation to international indirect taxes, this is certainly the case.
Client onboarding by way of correspondence requires stringent identity checks. Since the client is physically absent, the copy of the passport needs to be certified by a public notary. In many cases, such notarisation needs to be legalised by an apostille under the Hague Convention. This results in complicated and expensive onboarding activities. Also, financial institutions still run quite high risks because the passport and certifications can still be falsified.
Commerce is increasingly digital. Yet, the global tax system is still geared to the needs of a traditional ‘bricks and mortar’ economy. The OECD’s Base Erosion and Profit Sharing (BEPS) Action Plan recognises the need for modernisation and has achieved quite a lot since the issue of its reports in October 2015. However, specific recommendations on digital taxation have been limited and the OECD’s calls for an international consensus on the way forward have so far been unheeded.
Due to a change in Swiss VAT law with effect as from 1 January 2019 non-Swiss established distance selling businesses may become required to register for Swiss VAT. In cases where a non-Swiss established distance selling business generates an annual revenue from Swiss resident customers of CHF 100,000 from consignments that are import VAT free, it must register for VAT in Switzerland and charge domestic VAT on all its shipments to Swiss customers.
Grant Thornton Switzerland/Liechtenstein is continuing to expand its sponsoring activities and was presenting itself as the main sponsor of this year’s “Future Masters” Golf Tournament in Bad Ragaz for the first time.
The Double Taxation Agreement (DTA) between Switzerland and Liechtenstein has been in force since 1 January 2017. Swiss withholding tax on investment income payable from 1 January 2017 can be reclaimed in whole or partly by individuals and companies in Liechtenstein in 2018 for the first time.
In connection with developments concerning the EU Code of Conduct, Liechtenstein is planning significant amendments to the Tax Act with effect from 1 January 2019. The most relevant amendments can be summarized as follows:
Besides due diligence duties relating to anti-money laundering, financial institutions are also subject to those under the FATCA and AIA Act. The fiscal administration in Liechtenstein must monitor compliance with AIA and FATCA due diligence duties. Pursuant to Art. 11 of the FATCA Act and Art. 21 of the AIA Act, independent qualified public auditors or audit firms must carry out this monitoring. In the process, financial intermediaries may choose – in agreement with the fiscal administration – which audit firm is to conduct this statutory audit at their company.
Legal Tech is the name given to the emerging digitalization in legal work. The use of software and online services that support legal work processes are to make it possible to increasingly provide automated standardized legal services in future.